
AI agents in finance are moving automation beyond the limitations of traditional Robotic Process Automation (RPA). While RPA can follow predefined rules and automate repetitive tasks, AI agents can understand context, make decisions, take action across systems, and escalate exceptions when human judgment is required.
That shift matters because finance processes rarely follow perfectly predictable paths. Invoices arrive with missing information, reconciliations contain unexplained variances, approvals get delayed, and vendors require follow-up. Traditional automation often stops when these situations occur.
Most discussions around AI agents in finance remain theoretical. This guide takes a more practical approach. It explains what AI agents actually do, how they differ from RPA and chatbots, where agentic AI finance use cases are most valuable, how the technology works, and how finance leaders can implement it with appropriate controls.
The goal is not to automate everything. It is to determine where intelligent autonomy can create measurable value while keeping financial controls and human oversight intact.
What are AI agents in finance?
AI agents are software programs designed to perceive their environment, reason about what needs to happen, take actions, and adapt based on outcomes. Unlike conventional automation, which executes a predefined sequence, an agent can evaluate the current situation and determine the next appropriate step.
In finance, this means an AI agent can work with invoices, purchase orders, emails, ERP records, bank statements, approval workflows, and other financial data. It can determine what information is available, identify discrepancies, choose an appropriate action, execute that action through connected systems, and escalate the work when it cannot proceed safely.
For example, consider an invoice that does not perfectly match a purchase order. A traditional bot may stop because the predefined matching rule failed. An AI agent can examine the invoice, PO, goods receipt, historical transactions, and applicable policies to determine why the mismatch occurred. It may resolve a routine discrepancy, request clarification from the vendor, route the invoice to procurement, or escalate it to a finance employee.
This is the core idea behind agentic AI finance: using AI agents to perform goal-oriented financial work rather than simply automating individual tasks.
The distinction from RPA is important. RPA primarily follows rules. AI agents can reason about situations where the correct action depends on context.
The distinction from chatbots is equally important. A chatbot primarily communicates with users. An AI agent can communicate, but it can also take action inside business systems. It might update an ERP record, create an approval request, retrieve a bank statement, or trigger another workflow.
This makes AI agents particularly useful for processes that combine high transaction volumes with exceptions and judgment. For organizations exploring broader AI automation services, agentic capabilities can become another layer in the automation architecture rather than a replacement for every existing technology.
How AI agents differ from RPA and chatbots
RPA, chatbots, and AI agents are not interchangeable technologies. Each solves a different type of problem
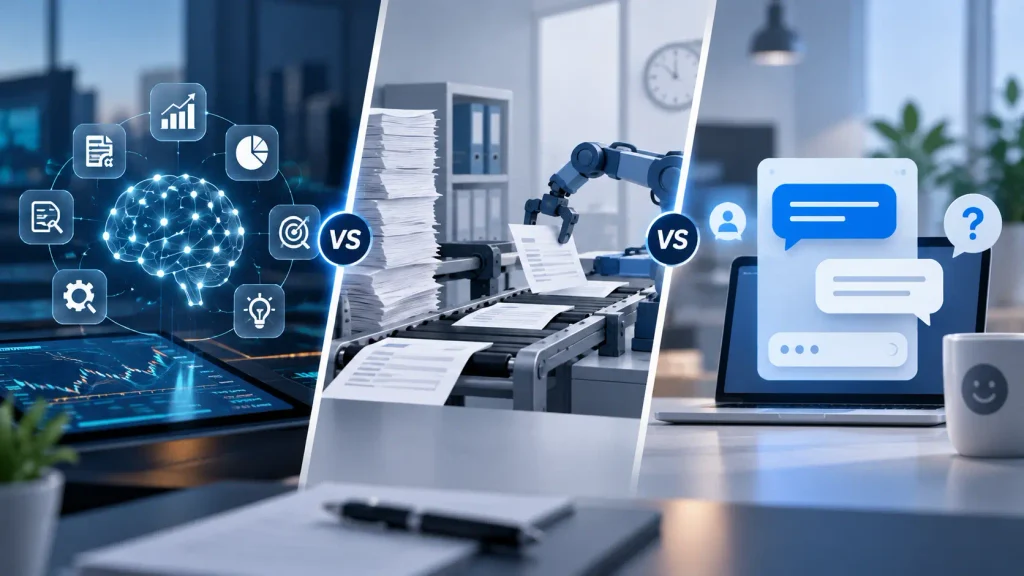
| Factor | RPA | Chatbot | AI Agent |
| What it does | Follows predefined rules | Answers questions | Plans, decides, and acts |
| Decision-making | None — if/then logic | Limited pattern-based responses | Reasons about next steps |
| System interaction | Usually UI-level automation | Typically limited | APIs and connected enterprise systems |
| Exception handling | Stops and waits | Escalates or deflects | Handles or escalates intelligently |
| Learning | Static unless redesigned | Limited | Can improve through feedback and evaluation |
| Typical use case | Repetitive tasks | Customer or employee support | Complex multi-step workflows |
| Human oversight | Required for exceptions | Required for escalations | Supervised through defined guardrails |
RPA is strongest when the process is deterministic. If the same input always produces the same output, a traditional bot can be fast, reliable, and inexpensive.
Chatbots are useful when the primary requirement is communication. A finance employee might ask a chatbot about an invoice status, payment policy, or account balance.
AI agents are different because they combine reasoning with execution. An agent might receive a request to investigate an overdue invoice, retrieve information from the ERP, check payment status, review vendor correspondence, determine the reason for the delay, and initiate the appropriate next step.
This does not mean AI agents replace RPA. In a mature finance automation environment, they complement one another.
RPA can handle deterministic steps such as moving structured data between systems. AI agents can handle judgment-based steps such as interpreting an exception or determining which workflow should happen next. Orchestration can then connect both technologies into one process.
This evolution is often described as from RPA to APA, where automation moves from individual scripted tasks toward intelligent, outcome-oriented processes.
The practical question for finance leaders is therefore not whether RPA or AI agents are better. It is which technology is appropriate for each step of the process.
AI agent use cases in finance
The strongest agentic AI use cases finance teams should consider are processes where high transaction volumes meet exceptions, multiple systems, and frequent human coordination.
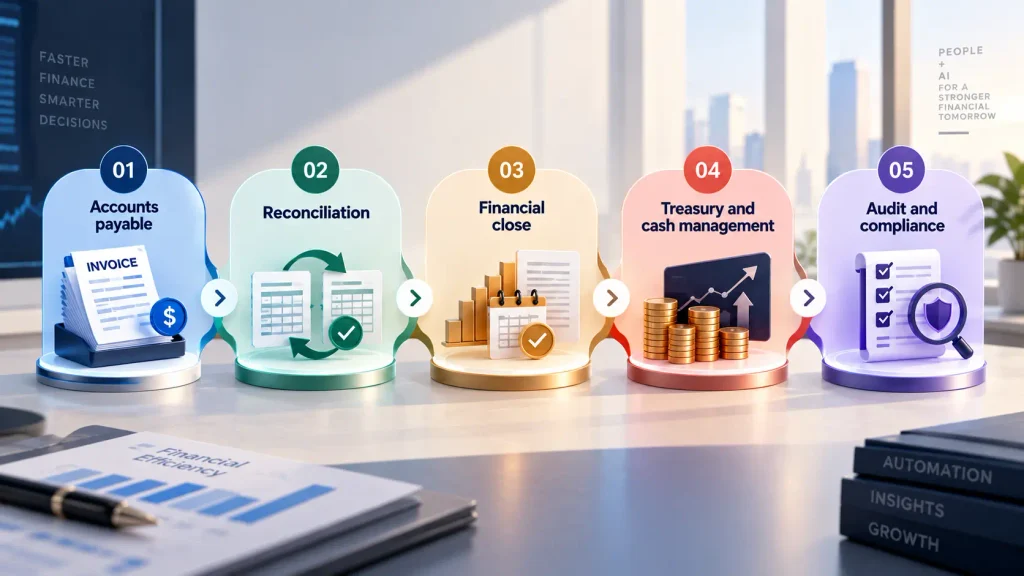
1. Accounts payable
Accounts payable is one of the most practical starting points for AI agents because the process contains repetitive activities as well as judgment-based exceptions.
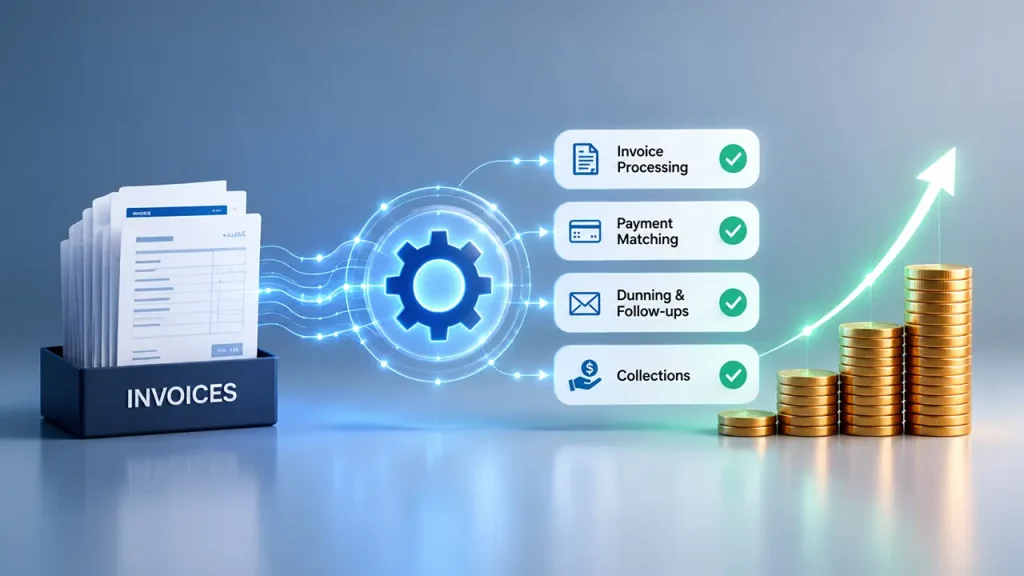
AI agents in accounts payable can support invoice capture, data extraction, validation, two-way and three-way matching, duplicate detection, approval routing, exception handling, ERP posting, and vendor communication.
A typical workflow could look like this: Invoice received → Data extracted → Invoice validated → PO matched → Duplicate checked → Approval routed → ERP updated → Vendor notified
Suppose an invoice has a quantity mismatch. Instead of simply stopping the process, the agent can investigate the purchase order and goods receipt, determine whether the discrepancy falls within an approved tolerance, and decide what should happen next. If the issue is outside its authority, it can route the exception to the correct employee with the relevant information already assembled.
This reduces the amount of manual investigation required by AP teams.
Organizations looking to automate the broader process can also explore AP automation services rather than treating invoice capture as a standalone project. The highest value often comes from connecting invoice processing, matching, approvals, exceptions, posting, and communication into one workflow.
2. Reconciliation
Reconciliation is another strong application for AI agents because finance teams frequently need to compare data from multiple sources and investigate unmatched transactions.
An agent can pull bank statements, compare transactions against general ledger entries, identify matching records, categorize differences, investigate common variance patterns, generate a reconciliation report, and escalate unresolved items.
For example: Bank statement retrieved → Transactions matched → Variances identified → Exceptions investigated → Reconciliation report generated → Unmatched items escalated
Rather than forcing every discrepancy through the same rule, an agent can consider transaction context and historical patterns before deciding whether an item is routine or requires human attention.
This can reduce manual matching and allow finance professionals to focus on the exceptions that genuinely require judgment.
3. Financial close
Financial close involves numerous activities that must happen in the correct sequence and within tight deadlines.
AI agents can coordinate close checklists, monitor task completion, prepare recurring journal entries, reconcile accounts, collect supporting documentation, identify missing items, generate reporting packages, and notify controllers about unresolved issues.
A close agent could run through the required checklist, determine which activities are complete, trigger the next available task, prepare recurring entries, verify reconciliations, and escalate items that fall outside predefined thresholds.
This creates a more coordinated close process rather than simply automating individual tasks.
4. Treasury and cash management
Treasury operations involve continuous monitoring and decisions that depend on current financial information.
AI agents can monitor cash positions, consolidate information from banking systems, support cash forecasting, identify potential liquidity shortfalls, and recommend actions based on defined policies.
For example: Cash positions monitored → 13-week cash flow forecast updated → Potential shortfall identified → Policy and available liquidity reviewed → Recommended action generated → Treasury team notified
For higher-risk decisions, the agent should recommend rather than execute. This is where confidence thresholds, approval limits, and human oversight become especially important.
5. Audit and compliance
AI agents can also support continuous monitoring rather than relying entirely on periodic reviews.
An agent can monitor transactions, identify unusual activity, compare transactions against defined policies, flag anomalies, collect supporting evidence, generate reports, and maintain an audit trail.
For example: Transactions monitored → Anomaly detected → Relevant records collected → Policy checked → Exception documented → Human reviewer notified → Compliance trail maintained
The objective is not to remove auditors or compliance professionals. Instead, agents can reduce the effort required to identify, organize, and investigate potential issues.
Across these use cases, the common pattern is clear: AI agents are most valuable when the process requires more than simply executing a fixed sequence of steps.
AI agent architecture for finance
Finance leaders do not need to understand the code behind an AI agent to grasp its architecture. At a practical level, an agent operates through four stages.
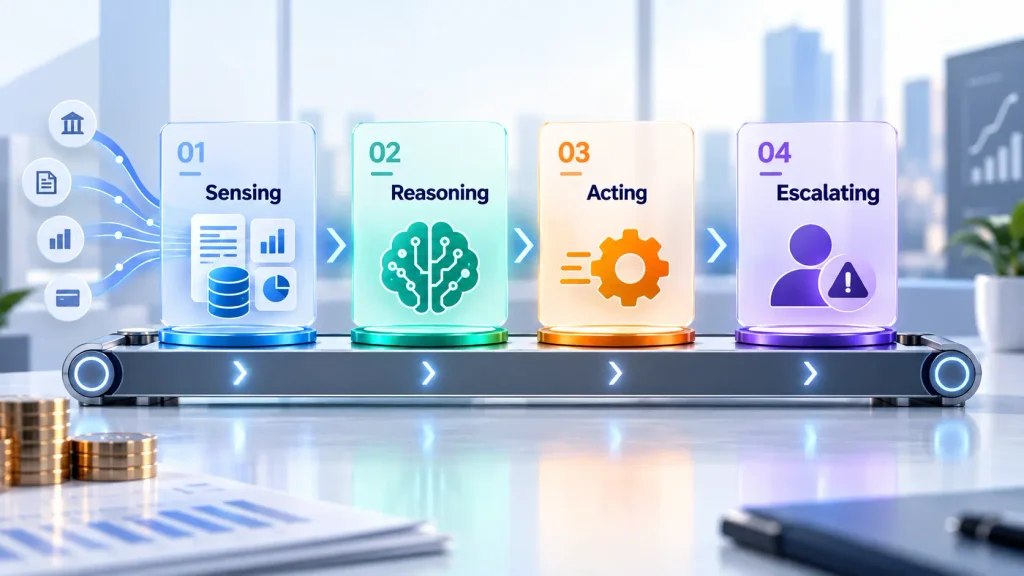
1. Sensing
First, the agent gathers information about the current situation. This could include invoices, emails, purchase orders, ERP records, bank statements, contracts, spreadsheets, or approval requests. The objective is to understand what is happening before taking action.
2. Reasoning
The agent evaluates the available information and determines what should happen next.
For example:
- Does the invoice match the purchase order?
- Is the variance within policy?
- Should the transaction be approved?
- Does this item require additional documentation?
- Should the issue go to procurement or finance?
This is where agentic AI for finance differs most clearly from conventional automation. The agent is not simply executing a fixed sequence; it is selecting the next action based on context, policies, and available information.
3. Acting
Once the next step has been determined, the agent uses connected tools and systems to execute it. This may involve updating an ERP, sending an email, creating an approval request, retrieving information through a banking API, posting a journal entry, or updating a workflow.
4. Escalating
A well-designed finance agent also knows when not to act.
If confidence is low, a policy is violated, an exception exceeds its authority, or the available information is incomplete, the agent should escalate the task to a human.
Multiple agents can also work together through orchestration. For example, an AP agent could process an invoice, a reconciliation agent could validate related transactions, and a close agent could incorporate the results into the month-end workflow.
The agents do not need to replace existing enterprise systems. They can use ERP APIs, document-processing tools, approval platforms, banking APIs, email systems, and other tools to coordinate work across the finance technology stack.
Governance, auditability, and human oversight
Finance cannot adopt autonomous technology without addressing control. An AI agent may be able to make decisions, but financial organizations still need to know what happened, why it happened, who approved it, and whether the action complied with policy.
Five governance principles are particularly important.
Human-in-the-loop: Agents should escalate exceptions rather than silently failing or making decisions outside their authority.
Audit trail: Every important action should be logged, including what the agent did, when it did it, why it took the action, and whether a human approved the outcome.
Confidence thresholds: Agents should operate autonomously only when confidence is above a defined threshold. Lower-confidence situations should be routed for human review.
Policy enforcement: Approval limits, segregation of duties, authorization rules, and other finance policies should be embedded into the workflow.
Rollback capability: Where technically possible, actions should be reversible so that incorrect transactions or workflow decisions can be corrected.
Governance should also extend to measuring how well the agent performs over time. Finance leaders can use agentic AI metrics and KPIs to evaluate task success, accuracy, autonomy, exception handling, efficiency, and robustness. The goal is controlled autonomy, not unrestricted autonomy.
How to implement AI agents in your finance team
Implementing AI agents in finance works best as a phased process rather than an enterprise-wide transformation launched all at once.
Step 1: Start with one process
Choose a high-volume, measurable process. Accounts payable is often a practical starting point because it contains repetitive activities, exceptions, approvals, and clear performance metrics.
Step 2: Map the current process end-to-end
Document every stage, including handoffs, systems, approvals, bottlenecks, and exceptions. Do not map only the happy path. The exceptions often determine whether an agent will deliver meaningful value.
Step 3: Separate deterministic work from judgment-based work
Identify which steps can be handled through traditional RPA or workflow automation and which require contextual interpretation or decision-making.
Step 4: Build the agent around judgment-based steps
Give the agent access only to the information and tools it needs. Define what it can decide, what it can execute, and what it cannot do.
Step 5: Add human-in-the-loop controls
Create clear escalation paths for exceptions, low-confidence decisions, policy violations, and high-value transactions.
Step 6: Define confidence thresholds and escalation rules
Do not leave autonomy undefined. Establish measurable rules for when the agent can proceed and when a person must review the work.
Step 7: Measure and iterate
Track metrics such as touchless processing rate, exception rate, cycle time, accuracy, human intervention, and cost per transaction.
Step 8: Expand to the next process
Once the first implementation is stable and producing measurable results, extend the architecture to reconciliation, close, reporting, treasury, or other finance workflows.
With the right process, technology, and implementation partner, a focused finance automation initiative can typically move from assessment to a working solution in approximately 6–8 weeks. Broader transformations will naturally take longer depending on process complexity, ERP environments, integrations, and governance requirements.
Organizations that need help moving from strategy to implementation can consider intelligent automation services or finance transformation consulting to assess processes, select the right technology, and build a scalable automation roadmap.
Real results and case studies
The business case for AI agents in finance should ultimately be measured through operational outcomes, not AI capabilities alone.
Auxiliobits’ published finance automation results include a 40–60% reduction in manual finance work, $200K+ in annual savings, 9,700+ hours recovered annually, a 73% reduction in close processing time, and 2–3x faster invoice processing. These figures come from client engagements and should be treated as examples of achievable outcomes rather than universal guarantees.
These results also show that meaningful improvements extend beyond traditional RPA. As automation evolves toward agentic workflows, AI agents can address the judgment-heavy steps that previously required manual intervention.
For finance leaders, the opportunity is to combine deterministic automation, AI, orchestration, and human oversight into a connected operating model.
Read more about agentic process automation and explore the case studies to see how automation has been applied across finance and enterprise operations.
Ready to move from theory to implementation?
AI agents can help finance teams move beyond isolated automation toward intelligent, connected processes across AP, reconciliation, close, treasury, and compliance. The right starting point is not the most advanced AI technology—it is the finance process where better automation can create measurable value.
Ready to explore AI agents for your finance team? Book a discovery call to see how AI agents can transform your AP, reconciliation, and close processes.